
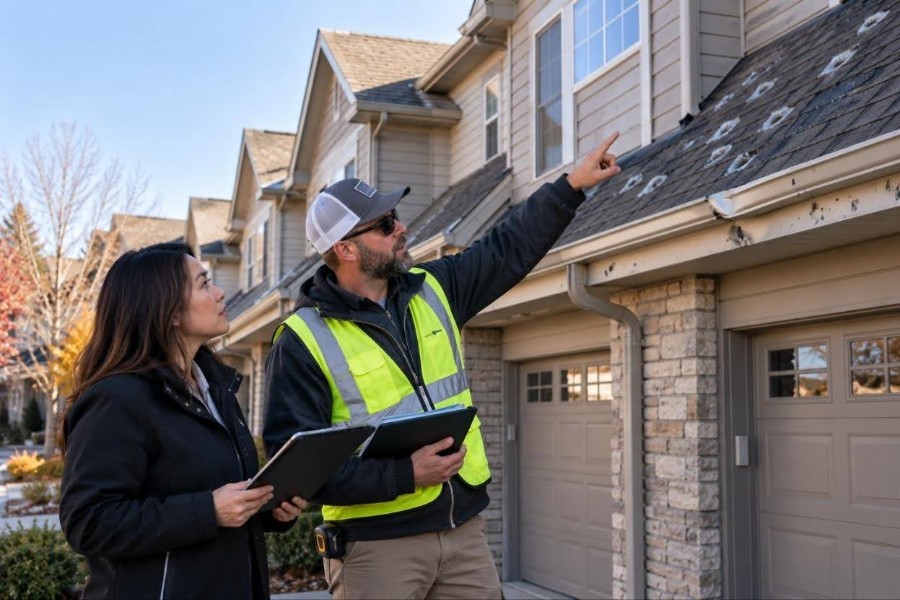
When a hailstorm damages a townhouse community, the insurance carrier does not manage the association’s project for it. Someone still needs to gather photos, schedule inspections, communicate with residents, track decisions and coordinate repairs.
That is where an HOA management company can add value, but the manager’s role should be clearly defined in the management agreement. Claims involving major restoration can require substantially more work than routine property administration.
What Happens After a Claim Is Reported?
1. Triage and emergency protection
The immediate priority is protecting people and preventing further damage. A manager can coordinate emergency vendors and help the board document actions taken. Emergency work should be limited to what is necessary until coverage and the full repair scope are better understood.
2. Gather facts and notify the right parties
A manager can organize the incident date, affected buildings, photos, owner reports, contractor observations and policy information. The board or authorized representative decides how and when to notify the insurer, with advice from the insurance agent.
3. Coordinate adjuster access
Large claims can involve several buildings and occupied units. Management can arrange access, keep appointment records and communicate inspection schedules.
4. Organize contractor proposals and professional reviews
An adjuster’s estimate, contractor proposal and engineer’s report may not describe the same scope. Management can assemble the documents and flag gaps for the board. The insurer determines coverage; engineers and qualified contractors evaluate technical issues.
5. Track approvals, payments and repairs
The board should approve contracts under its governing documents. Management can track deposits, change orders, insurance proceeds, deductibles, invoices, completion milestones and warranty documents.
What Is Usually Outside a Manager’s Authority?
A property manager should not promise that the insurer will cover a loss, provide legal opinions about disputed coverage, act as a licensed public adjuster without required authorization, or approve major expenditures beyond delegated authority.
A manager also should not decide that an owner’s personal insurer must pay a particular deductible. Coverage decisions belong to the relevant insurers, and legal allocation questions may require counsel.
Is Insurance Claim Management Included in the Base Management Fee?
Not necessarily. Routine incident reporting may fall within ordinary services, while extensive claims administration, construction coordination, after-hours response and multi-month restoration may be separately compensated if the agreement permits it.
Before a claim becomes a large project, boards should ask:
- Which claim-related tasks are included?
- Which services require additional fees or a separate agreement?
- Who approves emergency spending?
- Who handles owner unit access?
- Who monitors construction quality?
- Who reconciles proceeds, deductible and vendor payments?
Transparent scope prevents disputes at the worst possible time. For a broader overview of the policies involved, read Understanding HOA Insurance: What Minnesota Associations Should Know. For responsibility questions after damage, see Who Is Responsible for HOA Repairs in Minnesota?.
Minnesota Scenario: One Storm, Three Different Workstreams
A 36-unit condominium association in the east metro experienced hail damage. The roofs may be association property, several owners report interior stains, and the deductible is significant.
A well-organized claim file separates three workstreams: insurance coverage, construction and repairs, and financial allocation. Combining all three into one email thread invites confusion. Management can maintain separate logs so the board knows what has been approved, what is disputed and what remains unresolved.
What to Do Next
Review your management agreement before the next storm. Confirm the claim reporting contact, emergency authorization limits, additional-fee schedule and the board’s approval process. Ask the insurance agent to explain the deductible with a realistic example.
For general resources, visit EPMI’s HOA resource center. If your board needs help with vendor coordination, documentation and consistent communication, learn about EPMI’s Minnesota townhouse and condominium management services.
A major claim should not depend on one volunteer’s inbox. Contact Exclusive Property Management Inc. to discuss structured association management.
Frequently Asked Questions
Does the HOA manager decide whether a claim is covered?
No. The insurer makes coverage determinations under the policy.
Does the manager hire the repair contractor?
Management may solicit and coordinate proposals, but the board’s delegated authority and governing documents control contract approval.
Can the management company charge an additional claim administration fee?
It depends on the management agreement and any approved supplemental scope. Fees should be disclosed and authorized.
Who communicates with homeowners during a claim?
The board should establish a single communication process. Management often assists with scheduling, notices and updates.
Who handles repairs inside an individual unit?
Responsibility depends on the declaration, policy, cause of loss and applicable law. It should not be assumed from physical location alone.